Category: Investments

Blog

Georgia Flood Insurance Requirements

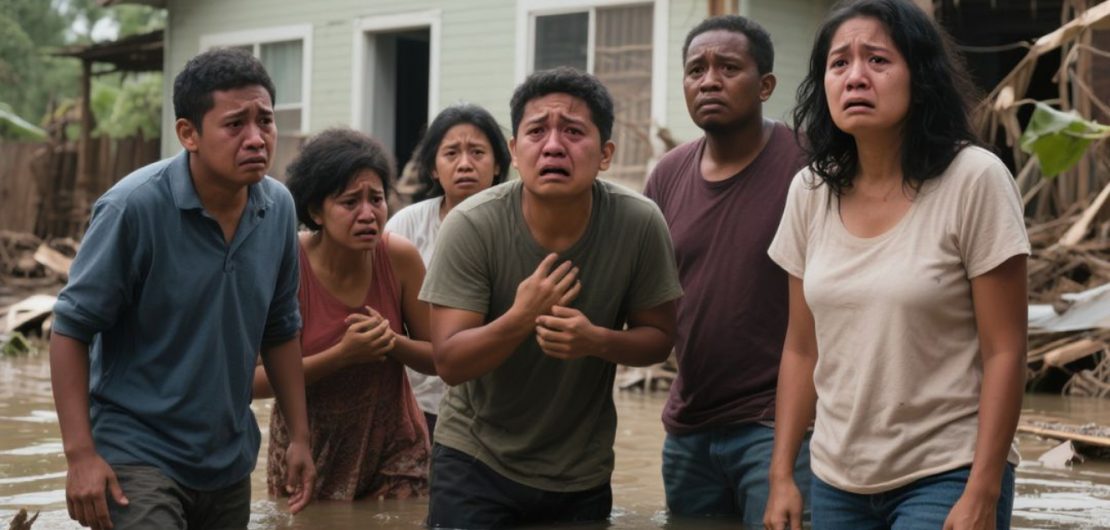
The Peach State of Georgia is no stranger to floods. They frequently follow thunderstorms and cause widespread damage. The Federal Emergency Management Agency (FEMA) says that even just 1 inch of floodwater can lead to $25,000 in damage. 

In Georgia, homeowners can expect to pay about $142,000 or more in flood damages over the course of a new 30-year mortgage, according to a study by the Natural Resources Defense Council (NRDC), an environmental advocacy organization. This puts the Empire State of the South in third place nationwide—right behind Connecticut and Alabama—when it comes to high flood-related costs. 

Another important finding of the study is this: Previously flooded homes are likely to experience more flooding in the future. Considering how costly flood damage can be, it’s important to take proactive actions to lessen its financial impact. One of the best ways to do that is to have the right flood insurance because most homeowners insurance don’t cover it.

What Requirements Must You Meet to Get Flood Insurance in Georgia?

Georgia has no state law mandating flood insurance for all homeowners and business owners. So, depending on where you live in the state, you might not need to apply for flood insurance. 

However, if your property meets all three of these conditions, you are required to purchase flood insurance.

1. Your house is located in a Special Flood Hazard Area.

You need to get flood insurance if your property is located in a Special Flood Hazard Area (SFHA) or the Floodplain. This is considered a high-risk area with a 1% annual chance to flood.

SFHAs are marked on the FEMA’s Flood Insurance Rate Maps (FIRMs) or simply, flood maps, with the letters “A” or “V.” These zones come with at least a 1 in 4 chance of flood during a 30-year mortgage. 

Meanwhile, moderate to low-risk areas are marked with the letters “B”, “C”, or “X”. While flood insurance isn’t required in these areas, it’s still strongly recommended for all property owners, most especially because more than 20% of flood claims come from the outside high-risk areas. 

2. Your community participates in the National Flood Insurance Program. 

If your property is situated in a National Flood Insurance Program (NFIP) participating community, then you’re required to get flood insurance. 

The NFIP is the most common type of flood insurance in the state. The program is run by the FEMA and offers standardized policies for property owners, renters, and businesses. 

3. You are required to have one by your mortgage lender. 

If your house is under mortgage, most lenders may require you to get flood insurance if your property is in a high-risk flood zone. You are also required to have one if you have a mortgage from a federally regulated or insured lender. 

Why Does Flood Insurance Matter?

Once you are aware of the potential flood risk, having the right coverage is essential to safeguard your home or business. As the name suggests, flood insurance is designed to help cover the damages directly caused by flooding. 

Damages caused by this natural risk are typically not included in most homeowners’ insurance policies. Thus, if your home floods and you don’t have flood insurance, you could face costly repairs that you have to pay for on your own.

Having flood insurance can help you avoid unexpected out-of-pocket expenses. Policies typically include two types of coverage: one for the building itself and another for what’s inside. The coverage in these arrangements depends on several factors, such as the location of your home, the property’s age, and the manner it was built.

What Happens If You Don’t Have Flood Insurance?

Georgia has a total of 159 counties, but only 584 communities participate voluntarily in the NFIP, according to Georgia’s Environmental Protection Division. This means 89% of the state’s mapped Special Flood Hazard Areas (SFHA) are covered. 

Seventy-one communities mapped with SFHAs don’t participate in the NFIP. For these communities, the consequences can be dire: 

  • People in the community, despite their desire, won’t be able to acquire flood insurance policies;
  • There will be no federal grants or loans that can be used to build or buy properties in areas marked as flood hazard areas;
  • There will be no federal disaster assistance for building repairs; and
  • There will be no federal mortgage insurance or loan guarantees to be provided
How to Get Flood Insurance

It is incredibly difficult to recover from a devastating calamity such as a flood. That is why, if you have decided that flood insurance is the right move to protect your most valuable assets—whether it’s your home or your business—the next action is to know how and where to get it. 

With many communities in Georgia with mapped SFHA taking part in the NFIP, this program is the most common way to find an insurance provider.  The NFIP partners with these participating communities to help reduce the financial impact of floods. Aside from the SFHAs, the NFIP also provides both building and contents coverage for moderate to low-risk areas through its Preferred Risk Policy. 

The NFIP flood insurance coverage limits vary based on property type:

Property TypeMaximum Building CoverageMaximum Content Coverage
Residential properties for a family of 1-4$250,000$100,000
Residential properties for a family of 5 or more$500,000$100,000
Commercial properties$500,000$500,000

Source: Federal Emergency Management Agency (FEMA)

Aside from homeowners and business owners, renters can also apply for flood insurance to cover the contents of their rented homes or properties. It is important to note that there’s a 30-day waiting period before coverage starts, so don’t wait for a flood warning to apply. You can purchase flood insurance through your insurance company or agent.

Cost of Flood Insurance

Like flood insurance coverage limits, premiums vary and aren’t one-size-fits-all. The NFIP uses a property-specific approach to determine the cost of coverage. Such an approach considers several factors to determine a property’s risk, such as the following:

  • How likely is your property to experience different types of flooding (flash floods, coastal erosion, or high water levels from storms)?
  • What are the features of your home (like foundation type or first-floor elevation)?
  • How far is your property from rivers, lakes, or coasts, and its elevation from those flood sources?
  • How much would it cost to rebuild your home after a flood?
  • Does your home have flood-resistant features, such as flood vents, which help reduce potential damage?
  • Are there levees nearby, and how well can they protect your area during a flood?
Why Flood Insurance Is Worth It

Contrary to what most people think, flood insurance is not just an added expense. It is a smart and proactive investment, especially for your peace of mind. 

When you weigh the potential cost of flood damage against the price of a premium, the benefits become clear. A few inches of water can cost tens of thousands of dollars. Paying a manageable amount each year or monthly installments helps you avoid the overwhelming financial burden of repairing or rebuilding your property after a destructive flood. 

By transferring the risk to an insurance provider, you are protecting not only your home or business but also your financial stability. In a state like Georgia, where flooding can happen almost anywhere, having flood insurance means you are prepared no matter what comes your way. It helps ensure that you are not left vulnerable when a flood happens.


While you can’t always predict a flood and the damage it can do, don’t wait for it to happen before taking action. Flood insurance is more than a policy. It is your safety net when the waters rise.  
Blog

What are the Disadvantages of Owning Commercial Property?

If you own an apartment building, a warehouse or a retail space, what you have is a commercial property. Unlike a residential real estate, a commercial property doesn’t serve as a home for people. Instead, it is used for business, as a workspace, or for other income-generating activities.

Commercial properties can be categorized into four classes: multifamily rental, office space, retail, and industrial properties. They can include a wide range of real estate properties, such as office buildings, apartment buildings, warehouses, hotels and resorts, restaurants, strip malls, and healthcare facilities.  

A well-run commercial property could benefit greatly from having the following (we’ll discuss in greater detail later):

  • Property Management company
  • Commercial Insurance
  • Public Adjuster to manage insurance claims
  • Regular maintenance and repair services to ensure the property remains in top condition
  • Security services to safeguard the property and its tenants
  • An energy management system to optimize energy use and reduce costs

However, to be considered a commercial property, the owner must have bought it for the sole purpose of earning a return through price appreciation or capital gain, or rental income, or both. Commercial properties are typically leased by businesses, except in the case of multifamily rentals and apartments. 

Because they appreciate in value and have the potential to generate income for the owner, commercial properties are good investments. It’s a stable source of income too, one that doesn’t perform poorly even through market shocks. A major factor for this stability is that tenants of commercial properties often lease them for a longer period compared to residential real estate. And, the rental rates are higher too. 

However, despite these and other benefits, commercial buildings also come with some disadvantages. Let’s discuss several of them below. 

Higher Initial Investment or Cost of Ownership

Generally speaking, commercial properties are more significantly expensive than residential real estate. There are several factors contributing to this high price, including limited availability, prime locations, potential for higher rental yields, reputable tenant demand, and development costs.  

Even if it’s a small commercial property, it will still be expensive. Commercial property investors will need a substantial down payment and closing costs, not to mention other expenses necessary to lease and operate it. In other words, you will typically need a huge chunk of capital to buy a commercial property no matter the size. 

Because the upfront investment is significant, commercial property investors also shoulder the potential risk of losing a huge amount of capital.  

Bigger Renovation Costs

Shelling out money to purchase a commercial property is just one of the costs of owning one. Once you have a commercial real estate under your name, you still have to do tons of work to make the space suitable for leasing out. 

One such expense is renovation, the costs of which can stack up depending on the tenant’s needs. According to accounting software firm FreshBooks, you could pay less than $30 per square foot to more than $300 per square foot for renovating a commercial property. The actual cost will depend on several factors such as location, building codes, building use, building materials, and labor cost. 

In addition to high renovation costs, commercial property owners also need to ensure that the amenities, security, and parking needs of the tenant are met. 

Legal and Regulatory Complexities

The law is a complex subject and navigating it can be complicated. In fact, regulations surrounding commercial real estate is a major roadblock or hindrance to prospective investors. 

There are rules and regulations on purchasing, maintenance, and taxes, for instance, and they can differ from state to state. Legal requirements might also vary for different industries, zones, sizes, and zones, among others. The laws surrounding commercial leases are also stricter compared with residential lease agreements. 

If a commercial real estate investor is not careful, they could open themselves up to lawsuits and claims from not only tenants but also customers, employees, and contractors. That is why, most commercial property owners ask professionals who know their way around the law, such as lawyers and property management firms, to help protect their business.

More Intensive Property Management

Property management for a commercial property includes similar duties as those for residential property management. Commercial property managers also deal with tasks such as marketing, tenant screening, rent collection, and regular maintenance. But, imagine those duties on a much larger scale. 

Because of the property’s size and the number of tenants involved, the scale of operations is just much bigger compared to that of a residential property. So, property managers of a commercial real estate need to possess expertise for efficient management. 

Higher Maintenance Cost

As with any real estate property, regular maintenance of a commercial property is necessary to preserve its value, keep its functionality, and ensure safety in its premises at the very least. Ongoing management, upkeep, and repair of the property is also important for optimizing performance and complying with relevant laws and regulations.

However, unlike residential properties, commercial real estate might require the use of specialized services and equipment for maintenance and repairs. As such, the costs are higher. 

The average annual maintenance cost for commercial properties ranges from $2 to $2.50 per square foot, according to the International Facility Management Association (IFMA), the world’s largest international association of facility management professionals. 

These costs vary based on factors such as location, age, and usage. For instance, commercial properties used for retail have lower average annual maintenance costs at $1.50 to $2 per square foot. Meanwhile, those used as offices incur an annual average maintenance cost of about $2.15 per square foot, according to the Building Owners and Managers Association (BOMA).

Exposure to More Risks and Liabilities

Although a commercial property has the potential to earn more than a residential property, it does come with more risks and liabilities. 

Public Safety

A commercial property, especially one that is used for retail purposes, typically has more public visitors. With more people on the property daily, the chance that these individuals can get hurt or do damage to the commercial real estate is much higher. Even if the injury or damage is minor, such as someone slipping and falling or vandalism, it still represents a liability for the owner. 

Credit Risk

While commercial leases represent a higher amount and go for longer periods than residential lease agreements, the risk of non-payment is also greater. Because we’re talking about significant amounts of money here, a business with declining sales or which suddenly closes poses a huge financial risk for commercial property owners. 

Businesses who can’t pay their lease will impact not only the property’s income but also its value. Then there’s also the cost of litigation to collect rent.

climate change insurance public adjuster Blog

How Will Climate Change Affect Property Insurance?

The insurance industry is raising rates, demanding higher deductibles, and even withdrawing coverage altogether in regions battered by climate change. For example, if you live in an area of the Midwest where they are historically somewhat immune to large natural disasters, you may not have to face unfortunate occurrences like:

  • Hurricanes
  • Tsunamis
  • Earthquakes
  • Mudslides
  • Volcanos

However, if your area doesn’t see the above happen often, chances are, you might face some other potentially disastrous natural occurrences such as:

  • Blizzards
  • Winter storms
  • Floods
  • Drought ((lack of precipitation, shortage of water in the environment, water restrictions, etc. may cause people to resort to alternative methods for watering gardens or agriculture, such as using irrigation systems or pumps. If not properly maintained or used cautiously, these practices can increase the risk of accidental fires and with dry conditions, will spread rapidly)
  • Hail
  • Lightening
  • Heatwave
  • Frigid, cold front
  • Wildfires (I would not have imagined this as a threat until recently when the wildfires happening in Canada directly affected our air quality in Michigan for almost the whole summer) To date, the following illuminates the extent of the fires and where they were geographically:
    • British Columbia: 7 million acres burned, more than double the old record.
    • Alberta: 5.5 million acres burned, nearly 2 million acres ahead of the old record.
    • Quebec: 12.8 million acres burned, more than double the old record.
    • Nova Scotia: 62,000 acres burned, about six times the old record of around 10,000 acres.

If you find yourself in one of these disaster-prone areas, it is crucial to fully understand your policy, especially if disaster strikes. If you do not, experts suggest hiring a private adjuster who will work with you and your trusted advisors as part of your claim recovery team.

Only a fraction of private adjusters have handled thousands of property damage claims of all sizes across multiple industries and regions. Some have almost a century’s worth of experience, with a unique insight into what is most important to large and niche industries throughout their region and how to best handle their property insurance claims. The right type of company will work exclusively for you, not the insurance company.

Be sure to do your research and find a company dedicated to representing property and business owners during the complicated claims process and one that will optimize the settlement you are entitled to receive under your property insurance policy.

Insurance rates climate change

Ok, so if the insurance companies’ reasoning on why rates are going up is because climate change is contributing to the uprising of natural disasters, then why are my rates so high when I do not live in a disaster-prone area?

In an article on APNews, they cited a recent report from First Street Foundation that states such as California, Florida, and Louisiana, prone to wildfires, damaging storms, and flooding, are likely to see the most dramatic increases in premiums. But the fire that destroyed the Hawaiian community of Lahaina on Aug. 8, 2013, as well as the historic flooding in Vermont and Maine in July, are examples of events that could drive up insurance costs for homeowners in other states.

Climate change is causing significant shifts in weather patterns, leading to increased extreme weather events, which can result in extensive property damage. As a result, insurance companies face higher claims costs and are forced to adjust their policies accordingly. This has led to rising insurance rates across the board, even in areas that were historically considered less prone to natural disasters.

One example would be how wildfires have now become a significant concern with climate change. Extended periods of drought and hotter temperatures have created the perfect conditions for wildfires to occur and spread rapidly. As witnessed in recent years, wildfires are not limited to specific regions and can now affect areas that were previously considered low-risk.

Do you need a public adjuster?

With insurance companies changing their policy rules and regulations, having a professional on your team is even more critical. These pros understand when clients ask questions like, “Ok, but do we really need a public adjuster? I’ve worked with my agent for more than twenty years. “They suggest thinking of it this way. If you sell your property, you work with a realtor to get the best possible outcome. If you are dealing with the IRS, you hire an accountant to get the best possible outcome. If you suffer property damage, you should hire a professional public adjuster to get the best possible outcome from your claim.

Basically, a policyholder will hire a public adjuster to assist in filing a claim and to ensure a satisfactory settlement. You can determine if hiring a public adjuster and paying this fee is appropriate for your situation, depending on the size of the claim and the amount of damages.

While it may seem tempting to rely solely on your insurance agent when filing a claim, the expertise and advocacy of a public adjuster can make a significant difference in the outcome of your settlement. From navigating complex insurance policies to accurately assessing damages and negotiating with insurance companies, a public adjuster protects your interests and ensures a satisfactory resolution to your claim.

Value of a public adjuster

Public adjusters, distinct from insurance company adjusters, work on behalf of policyholders. Their primary role is to prepare, present, and negotiate insurance claims to ensure policyholders receive fair compensation for their losses. With extensive experience in dealing with insurance companies and an in-depth understanding of policy language, they are well-equipped to maximize your claim’s potential.

Their familiarity with the intricacies of insurance claims sets them apart as advocates in what is often the largest financial transaction of someone’s life. Their expertise extends to assessing the full scope of damage, identifying hidden costs, and accurately valuing your losses. By having a public adjuster on your side, you gain a dedicated professional who will meticulously examine your policy and vigorously negotiate to secure the best possible outcome for you.

How will climate change affect property insurance?

In conclusion, climate change directly and indirectly impacts insurance rates across various regions. The increasing frequency and severity of natural disasters are leading to rising claims costs, prompting insurers to raise rates to mitigate their own risk exposure. Even areas previously considered less prone to such events are experiencing higher insurance costs as the effects of climate change continue to unfold. Property owners must be aware of these changes, understand their policy coverage, and explore options for mitigating risks.

Blog

Should I Refinance My Mortgage?

Refinancing your mortgage means getting a new mortgage to pay off your old mortgage. In other words, you’re getting a new loan on your house to pay off an existing one, and many people get refinancing for various reasons.

First of all, it’s easier to get refinancing than securing another loan. Other reasons include getting a lower interest rate, shortening your mortgage term, switching your loan terms, consolidating debt, or to raise funds. 

However, one thing you should remember is this: Refinancing can either save you money or cost you money. Refinancing interest rates range from 3% to 6% the loan’s principal and it will also incur application fees.

Refinancing would also entail title search and an appraisal. With all of these into consideration, when is it wise to refinance your mortgage and when is it unwise to do so? Let’s find out below. 

Instances When Refinancing Your Mortgage Makes Sense 

There are a number of situations when taking a refinancing agreement makes sense. These include: 

Refinancing Your Mortgage to Lower Your Interest Rate

The no. 1 reason you should refinance your mortgage is to lower your interest rate. The rule of thumb here is to refinance if you can reduce your current interest rate by 1% or more. In this way, you can save money. You can use a mortgage calculator, such as this one from Investopedia, to calculate the costs of refinancing. 

Other benefits for entering a refinancing agreement when current interest rates are low is to build your home equity faster. Equity is the fair market value of your house minus the amount you still owe. You build equity by paying off the loan principal or making payments on your mortgage. 

In addition, refinanced mortgages at lower interest rates can also reduce your monthly payment. For instance, imagine keeping $100 that used to go to mortgage payment every month – It can go a long way. In a year, you’ll have saved $1,200!

Refinancing Your Mortgage to Shorten Your Mortgage Term

Another good reason to enter a refinancing agreement is to shorten your mortgage term.

When you do this, you can own your house sooner. Typically, shortening your mortgage term results in lower interest rates but an increase in monthly payments. So, it’s essential that you do the math first before signing on a refinancing agreement to ensure you can afford the new monthly payments. 

Refinancing Your Mortgage to Lengthen Your Mortgage Term

Refinancing your mortgage may also be a wise move if there’s been a change in your income and you are having trouble making the monthly payments. With a refinance agreement, you can lengthen the term of your mortgage to lower your monthly payments to a more affordable amount. However, bear in mind that the new loan may have a slightly higher interest rate and you’ll likely end up paying more interest over time. But, it does free up some cash that you can use for other things, such as necessities or investments. 

Refinancing Your Mortgage for Renovations or Home Improvements

If you’ve been living in your house for several years now, chances are that something needs fixing or updating, such as a broken HVAC or outdated kitchen or bathroom fixtures. These upgrades can add curb appeal and increase your house’s value so that you can get more money when it’s time to sell your house. 

While you could get a personal loan or charge your credit card for home improvements or renovations, a cash-out refinance typically has a lower interest rate. Just remember that you should get an estimate from contractors and other repair professionals so you don’t end up taking too much or too little cash from the refinancing. 

Refinancing Your Mortgage to Increase Your Retirement Savings

If you haven’t maxed out your annual retirement contribution limits, you could take on a refinancing agreement to do so. You can use the money from a cash-out refinance and invest it into your retirement savings.

Refinancing in These Situations Can Be Good or Bad –  It Depends 

There are a couple instances when refinancing your mortgage can be wise or unwise, depending on several factors. You’ll have to examine your particular situation, do the math, and decide if a refinance makes sense for you or not.

Switching loan terms

When you mortgage your house, you can do so either as an adjustable-rate mortgage (ARM) or a fixed-rate mortgage. The difference between the two lies in the interest rate applied to your loan. ARM typically has a lower interest rate at the start of the loan but it fluctuates after several years due to periodic adjustments and the change isn’t always in your favor, whereas a fixed-rate mortgage applies a fixed interest on your loan throughout its term. 

You might want to switch from ARM to a fixed-rate mortgage to eliminate the risk of paying a higher interest rate. Conversely, a switch from fixed-rate to ARM may be a smart move when interest rates are dropping or you plan to sell your home before the interest rate increases, but it involves some risk.

Should I Refinance My Mortgage?

Ultimately, the decision to convert from one mortgage type to another really depends on the interest rates and how long you plan to stay in your house. 

Investments

What Are the Methods of Funding?

For artists to fund their work, there are a few different ways to explore that we will cover. The most common way we found was through grants, which are usually given by government agencies or industry-specific foundations. These organizations, whose intention is to support the arts, are happy to give money to artists.

Since grants can be challenging to obtain, they also often have very strict guidelines about how the funds can be used.

Another option is to find a customer who has faith in you, your art and, ultimately, is willing to provide the necessary funding for your goals. Historically, this was the most common method of funding, but obviously, it has become less common since the industrial age.

You could also finance your work through sales, and of course, this is the most common method for visual artists, but it can be challenging to sell your work for a high enough price to make a profit. For example, a caricature artist must be on site, live, creating their art at local and regional events, zoos, aquariums, the list goes on. Bottom line is, these types of artists must continue to create new art to present to their potential customers in order to maintain a solid income.

Some artists are able to take on commissioned projects. This type of funding is much like finding a customer who has faith in you, but with the added bonus that the project is already outlined for you. The parameters for the project will be set beforehand and it will be your job as the artist to complete the project within those confines.

Another example of how a visual artist could be funded would be when a professional commercial photographer is hired to shoot, for instance, a hamburger for a local chain. That burger joint then commissions the photographer to take photos of their hamburger, paying them based on the “usage” of the images. Will they be on a billboard? In a national magazine? In an international food publication? Or just used on their menu and on their website? The cost depends on these factors.

Whichever method you choose, funding your work is a vital part of being an artist.

Suppose we are talking about all kinds of businesses other than just the arts; The following is a list of other options to explore.

Some of the best ways to get capital to grow your business:

  • Bootstrapping; the funding source to start with is yourself
  • Loans from friends and family. Sometimes friends or family members will provide loans
  • Credit cards (not the most brilliant move, though, use only in an emergency)
  • Crowdfunding sites (GoFundMe)
  • Bank loans
  • Angel investors
  • Venture capital

How many types of funding are there?

The three types of startup funding are equity funding, debt funding, and government grants. Equity funding is when you sell a portion of your company to an investor in exchange for capital. The benefit of this type of funding is that you do not have to repay the money, and it does not put you in debt. However, the downside is that you lose some control over your company, and you may have to give up a more significant percentage of the profits should the company become successful.

Debt funding is when you take out a loan from a bank or other lending institution. The advantage of this type of funding is that you can get the money you need without giving up any ownership stake in your company. The disadvantage is that you will eventually have to repay the loan with interest, which can put a strain on your finances.

Government grants are another option for startup funding. These are typically provided by federal or state governments and come with certain restrictions on how they can be used. However, they can be a valuable source of capital for startups that meet the eligibility criteria.

Do investors get their money back if the business fails?

An equity investor is someone who provides money for your business in exchange for an ownership stake in the company. Equity investors are often referred to as “venture capitalists” because they are usually willing to take on more risk than other types of investors, such as debt investors. If your business fails, equity investors will likely lose all of their investment. However, if your business is successful, they stand to make a significant profit. So, while they are prepared to lose their investment, they are also hoping for a big payoff if your business succeeds.

On the other hand, debt investors are typically banks or other financial institutions that lend you money that must be paid back with interest. If your business fails, debt investors may attempt to collect the money they are owed through collections or other legal means. However, if your business is successful, you will simply pay back the loan plus interest. As you can see, equity and debt investors have very different risks and rewards when it comes to investing in a business.

When a business fails, its investors do not typically get their money back. If the company has any assets, they may be sold off to repay creditors. However, collections can be difficult and time-consuming, and often only a fraction of the debt is actually repaid.

For example, if a company owes $1 million to its creditors, it may only be able to raise $500,000 through asset sales. In addition, loans from family and friends are often not paid back if the business fails. As a result, investors should be aware that there is a risk of losing their entire investment when investing in a startup.

How do independent artists get funding?

If you are an independent artist swimming in debt or financial fear — here are some resources that may be helpful to you:

Most artist investors like to see a return on their investment quickly, so they tend to invest in projects with a shorter timeline. That said, there are artist investors who are willing to support projects with a longer timeline, such as an album or a tour. If you’re looking for artist investors,

It’s essential to do your research and find people who align with your vision. Many crowdfunding platforms cater to independent artists, such as Kickstarter, Indiegogo, and PledgeMusic. These platforms allow you to set up a campaign and collect pledges from supporters.

You can also create a page on GoFundMe or Patreon, which are popular platforms for fundraising for personal causes. Whatever platform you choose, be sure to promote your campaign widely and offer rewards that will incentivize people to donate.

And whatever you do, do NOT forget to have your estate done by an attorney. When the artist Prince passed away, his multimillion-dollar estate ended up in probate, which is the last place you want it to be. Prince’s estate was finally settled after a six-year court battle as the late singer did not leave a will regarding his $156 million estate. After Prince died in 2016, his six half-siblings were named his legal heirs.

What are the methods of funding?

In conclusion, the best method of funding will vary depending on the project and the amount of money required. However, grants and private donations are generally the most reliable funding sources. Grants can be difficult to obtain, but they offer a stable source of funding that does not need to be repaid. Private donations can be more volatile, but they can also be a major source of funding for projects that are unpopular or lack government support. Ultimately, the best source of funding will depend on the needs of the project and the willingness of donors to support it.

Investments

Invest in Stocks or Real Estate?

When evaluating if it’s better to invest is stocks or real estate, there really is no easy answer. Many factors go into your decision, including personality, comfort with risk, lifestyle wants and needs and more.

The decision to invest in stocks or real estate significantly depends on timing. You can find very few stocks that would have beat buying beachfront property on the West Coast in the 70’s using debt, then cashing in twenty years later. Virtually no real estate could have beat the returns you earned if you invested in shares of Amazon, Apple or Google early on in the companies’ history, especially if you reinvested your dividends.

When making investment choices, you don’t have a crystal ball and timing is impossible to predict. But understanding types of investments is crucial when choosing the best strategy to help your money grow and foster financial security.

Real Estate vs. Stocks

Purchasing shares of stock means you are essentially buying a piece of a company. For example, if a company has one million shares and you own 10,000 shares, you own 1% of the company.

As the value of the shares grows, the value of your stock in the company also grows. Stakeholders elect the company’s board of directors to watch over the management, and they decide how much of the profit each year gets reinvested in expansion and how much gets paid out as cash dividends.

Stocks can be over- or under-valued very easily. Before investing, be sure to study the company as a whole, paying particular attention to how much of their profit is paid out as dividends. A good rule of thumb is that if a company is paying more than 60% of profits as dividends, make sure you are comfortable with the risk that they may not have enough cash flow to cover unexpected changes in the market.

Investing in real estate means are you are buying a physical land or property. Real estate can either be cash-generating or a recurring cost.  Recurring cost real estate can require money every month, like in the case of a vacant lot that requires taxes and maintenance while you find a developer interested in purchasing it.

Cash-generating real estate can be apartment buildings, rental homes, or strip malls where you pay expenses, and the tenants pay rent to you as the landlord, and you keep the difference as profit.

Each type of investment comes with benefits and drawbacks.

Pros and Cons of Investing in Real Estate

Is real estate the right investment for you? Understanding the pros and con can help you decide.

Pros of Investing in Real Estate

  • Cash flow. Real estate rent can provide steady, reliable cash flow on a consistent basis. Often, real estate investments only improve your cash flow in the long-term and then again when you sell them.
  • Limiting fraud. It is more challenging to be the victim of fraud in real estate investing. You are able to literally see the building or property and inspect it, you can run background checks potential tenants, and complete or oversee repairs.  With stocks, you have to trust the management and the auditors to do their jobs correctly.
  • Using debt. Using debt, or leverage, in real estate can be structured far more easily and safely than using debt to buy stocks by trading on margin.
  • Safety. Real estate investments have long been a solid inflation hedge to protect against a loss in the purchasing power of the dollar.

Cons of Investing in Real Estate

  • Time and effort. Real estate takes a lot of hands-on work when compared to stocks. There are many factors to consider, like managing tenant issues with repairs, gas leaks, the possibility of getting sued for building defects, and more. Hiring a property manager to take care of your real estate can mitigate some of the time investment but managing your property will still require occasional meetings and oversight.
  • Continued costs. Real estate will cost you every month if the property is unoccupied. Items like taxes, maintenance, utilities, and insurance must still be paid. If you find yourself with long term vacancy rates due to factors beyond your control, you may end up losing money every month.
  • Value. With a few exceptions, the actual value of real estate hardly ever increases when examined in inflation-adjusted terms. Keep in mind that even if the actual value doesn’t increase, you benefit from the power of leverage.

Pros and Cons of Investing in Stocks

Like real estate, investing in the stock market comes with its own set of pros and cons.

  • Longevity. Over 100 years of research have proven that despite all of the downturns and crashes, buying stocks, reinvesting the dividends, and holding them for long periods of time has been the greatest wealth generator in history.
  • Minimal work. Unlike running your own small business, owning part of a business through shares of their stock doesn’t require any work on your part (other than making sure the company is a sound investment). You benefit from the company’s results but don’t have to put in the time and effort to show up to work.
  • Access. You don’t have to be wealthy with huge sums of available cash to begin investing in the stock market. With certain mutual funds or individual stocks, you can invest as little as $100 per month. You can also look into the growing variety of microsaving apps that allow you to begin investing for less than $26.  Real estate requires significantly more money for your initial investment, as well as the cost of maintenance and improvements.
  • Liquidity. Stocks are far more liquid than real estate investments, meaning that during trading hours, you can sell your entire position, many times, in a matter of minutes or even seconds. You might have a real estate listing for weeks, months, or even years before finding a buyer.

Cons of Investing in Stocks

  • Investing Emotionally. Though stocks have been thoroughly proven to generate wealth in the long run, many investors are too emotional and unsteady to benefit fully. Psychological factors can cause them to lose money, panic selling during downturns when they should instead be buying.
  • Short-term volatility. The price of stocks can go through extreme fluctuations in the short-term. Your $90 stock may go to $20 or to $180. If you know why you own shares of a particular company, this shouldn’t alter your course. You can use the opportunity to buy more shares.  When you hold onto well-valued stocks over the long-term, the extremes are often smoothed out.
  • Stagnation. If you invest in companies that don’t have much room for growth, then your stocks may not look like they’ve gone anywhere for ten years or more during sideways markets.

Should You Invest in Stocks or Real Estate?

Both real estate and stocks can provide substantial long-term financial gain, and both come with their own set of risks. When choosing the right investment strategy, the best way to mitigate against that risk while taking advantage of the potential gains is to diversify as much as you are able and work with professionals who can guide your investments to perform optimally.

401k

Average Investment Management Fees

When you are just getting started with an investment management company, it can be overwhelming to understand all the ins and outs, the fees, and what exactly your investment manager does. When you think about your daily life, from filling your gas tank to picking up groceries, there is a cost to doing business. Investment management is no different, and the fees associated with it can add up if don’t know what to look for and aren’t paying attention. Let’s take a look at typical investment fees and then find out what an investment manager does

Investment fees are not all bad. They cover some important costs to help ensure that your investments are managed well. You want to make sure you’re getting good value from your investments without letting excessive fees cut into your returns.  

You should never invest in anything until you understand how it works. And that includes investment fees. Your investment management company should clearly outline any fees associated with services and answer any questions you have about where the money your spending is going.

The average fee for a professional financial advisor’s services is 1.02% of assets under management annually for an account of one million dollars (the industry average fee is 0.95% and decreases depending on the size of your account).

There are several types of investment fees. Let’s review several of the most common fees you’ll come across when you start investing.

Loads (sales commissions)

If you are putting money into a Roth IRA, you’re actually buying shares in a mutual fund. The investment manager you’re buying those shares from will get a percentage of the money you invest, otherwise known as a load. When you see the word load, just think of a sales charge or a commission; there are three types of loads:

  • Front-end load: When you invest in a mutual fund with a front-end load, you are charged when you put money into your retirement fund.
  • Back-end load: Back-end loads are charged when you take money out of your retirement account.
  • No-load: With a no-load fund, you aren’t hiring an investment manager, so you don’t have to pay commission. However, when the value of your fund goes up, the expenses—like an annual maintenance fee—will cut into your profits.

Advisor fees

When you invest in mutual funds, you’ll either pay your investment manager through a load (commission-only advisors), advisor fee (fee-only advisors) or some combination of both (fee-based advisors).

Expense ratios (annual fund operating expenses)

You’ve paid your investment manager, now you need to help cover the costs of running the mutual fund. That’s where the expense ratio comes in. Several fees that make up the expense ratio:

  • Management fees: The stocks that make up your mutual fund aren’t there because of magic. Your investment management company makes sure that only the best investments make the cut. These fees help them manage the fund well.
  • Distribution and service (12b-1) fees: These fees pay for the fund’s marketing costs—how much it takes to promote the fund.
  • Administrative fees and operating costs: These cover things like salaries for the fund’s managers, record keeping and research. Some funds are more expensive to run than others which will impact how high or low the expense ratio is.

Now that you know more about the potential fees, what does an investment manager do?

Investment management companies are designed to clarify, simplify and maximize potential returns on clients’ investments. Various investments are used to help clients reach their unique goals. Often investment managers will focus on three key areas:

Create Income for Retirement

Most of us intend to save for the day we retire or just slow down a bit. Making sure there’s enough steady income to live on, where it comes from, how much is needed, and how it affects taxes are just a few of the things that need to be addressed. Your investment manager is well experienced in answering these questions and has helped create income for countless of retirees over the years. They will help plan and navigate your retirement journey.

Focus on Growth

You may not be ready for retirement and you want your investments to grow sufficiently so that when you are, the financial portions of the transition will be seamless. Determining the right balance between different investments is critical to long-term growth.

Consolidate and Coordinate

Very often people have so many varied investments that their portfolios become almost impossible to track, let alone manage. Investment managers help you coordinate and consolidate investments in ways that focus on increasing efficiency and reducing unnecessary complexity. They provide you with a detailed statement of all your investments that can be viewed on one page, helping them make better long-term decisions.

Investment companies will have a clear management process. Your investment manager will walk you through their particular process, but it typically involves these basics:

Review

The starting point for any portfolio is to review where you have your current investments. Your investment manager will try to keep it as simple and straightforward as possible, so you may be disappointed if you’re looking for an inch-thick book with a detailed analysis of your life history. You should expect a concise, easy-to-understand, one-page synopsis.

Plan

Your investment manager may determine some of what you currently have invested in is worth keeping, should be tweaked a bit, or maybe needs to go. They will address questions about taxes, growth, income requirements, and planning strategies. You will get a simple, easy-to-understand plan that addresses your specific needs, and the best ways to structure your investments to reach your goals.

Execute

No job is over until the paperwork is done. Your investment manager will assist in completing all the documentation necessary to execute your plans. They coordinate rollovers, work with you to complete applications, and monitor transfers of money. And, at completion, they provide you with copies of everything needed for your files. The investment management company staff is there to answer questions and provide assistance every step of the way.

Monitor

Managing investments is an ongoing process, and that includes the continuous monitoring, and assessing, of your investments as well as your investment managers performance. You should expect results, not just strategies. Your investment manager should encourage regular conversation to discuss performances of their investments, how they compare to market averages and your expectations, and if changes need to be made to the plan.

Investments

Asset Management vs. Investment Management

Do you need an asset manager? An investment manager? It can be confusing when you are searching out someone to help manage your money and are looking for the most appropriate professional to help you achieve your financial goals. At the end of the day, asset managers and investment managers work towards the same goal of making money for their clients but how they do this is a little different. Asset managers usually work with affluent individuals or companies that have very large amounts of money to invest. Investment managers may work with any individual or company interested in investing. Asset managers often focus on a specific type of asset investment, like real estate for example, and create a long-term plan to ensure their client’s investments appreciate in value. Investment managers may supervise daily transactions related to a client’s investments or they can focus on specific types of investments, such as stocks or bonds.

Asset Manager

Asset managers work with wealthy clients and handle their investments in things such as real estate or business ventures. In addition to finding investment options for clients they also work to find ways to save clients money or maximize their profits on existing investments. This requires they be detail-oriented and capable of making effective decisions.

Investment Manager

Investment managers may fill multiple roles. They can specialize in stocks and provide insight to their company’s research department about stock options for clients or they may focus on which investments to include in a client’s portfolio.

Why is investment management important?

Your investment manager is there to manage your investment portfolio. They will devise and implement an investment strategy to meet your goals, and then use that strategy to decide how to divide your portfolio among stocks, bonds and other investments. The manager buys and sells those investments for you as needed and also monitors your portfolio’s overall performance to ensure it stays on track with your goals in mind.

You may also find an investment manager that is also a financial planner. They can provide holistic financial advice for a variety of areas like cash-flow management, taxes, insurance and estate planning. Another option is a wealth manager, who often works with high-net-worth clients to manage their financial planning and investment management needs, as well as coordinate the services of other professionals, such as lawyers and accountants.

Investment management is important because it is very common to end up with an assortment of investment accounts — for example, you may have several IRAs, multiple 401(k)s from former jobs, or that brokerage account you opened on a whim. Investment management can organize your financial situation by consolidating accounts from different firms under one roof, allowing you to simplify and execute a cohesive investment plan.

When choosing an investment management firm, know that most require you to set up an investment account with them or at a brokerage they use. They will help you transfer your money from accounts at other firms, including retirement plan assets, IRA’s and any other financial account you are looking to streamline into your investment plan.

However, even if all of your investments are under one account, investment management is important if:

  • You want a second option about your investment decisions. You are not a financial expert and working with a professional can increase your investment confidence.
  • You need someone to keep an eye on your portfolio and rebalance assets when the mix drifts away from your finical goals.
  • You have complex financial issues, including things like family inheritance distributions, retirement-income planning, tax strategies or future legacy planning for your children and grandchildren.
  • You need an professional to help manage other financial needs. This may include things  like cash-flow planning, insurance decisions, portfolio distributions or debt management solutions. 

Your manager’s investment decisions are based on many factors, but they will start with your savings goal and your desired time frame. Savings goals can include things like emergency fund building, retirement, education, or large purchases like a home or cares. You will provide them answers and insight that helps them assess your risk tolerance, or your ability and desire to endure swings in investment returns and how you are prepared to handle stock market fluctuations. Your manager’s investment strategy is also informed by historical performance, market performance tax efficiency and investment fees – these are all taken into account when looking at your portfolio as a whole.

Managing investments is an ongoing process, and that includes the continuous monitoring, and assessing, of your investments as well as your investment managers performance. You should expect results, not just strategies. Your investment manager should encourage regular conversation to discuss performances of their investments, how they compare to market averages and your expectations, and if changes need to be made to the plan.